Committee OKs $44,087 in project invoices
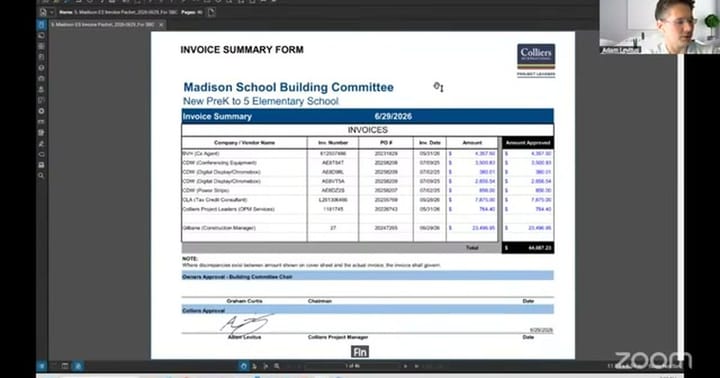
A Madison building committee approved $44,087.23 in project invoices and confirmed a $2.17 million tax credit value. The panel's unanimous vote covered invoices from BVH, CDW, CLA and Colliers totaling $20,590.28 plus a $23,496.95 payment requisition from contractor Gilbane.
Other Committee · Meeting of June 29, 2026
MADISON — A Madison building committee approved $44,087.23 in project invoices and confirmed a $2.17 million tax credit value. The panel's unanimous vote covered invoices from BVH, CDW, CLA and Colliers totaling $20,590.28 plus a $23,496.95 payment requisition from contractor Gilbane. Officials said the federal tax credit, tied to the Inflation Reduction Act, came in "a little bit higher" than the roughly $2 million long projected, with consultant CLA still finalizing an audit.
An 11-month warranty walkthrough the prior week found ongoing HVAC problems, including rooms on the building's northeast side "running a little bit hotter than others," and unresolved grass-establishment issues outside, with crews aiming to close out items before the one-year warranty period ends.
In the full story:
- Who Was There
- Organizations And Documents Referenced
- The complete report — 1,665 words
Source: the Other Committee meeting of June 29, 2026, reported from the official video recording and transcript.
Checked against the record: before publication this article was automatically compared with the meeting transcript.
The Full Article
Project Financing and Tax Credit Confirmation
Background and stakes: The committee has been tracking an anticipated federal tax credit tied to its capital construction project for roughly two years, with an earlier working estimate of about $2 million. The credit's final value affects the project's net cost once submitted to federal authorities, and the committee's outside consultant, CLA, has been completing the audit work required before that submission can occur.
The question before the body: Members were being updated on the final confirmed dollar value of the project's Inflation Reduction Act tax credit and the status of the paperwork needed to submit it.
Substantive content: A project representative told the committee a multimillion-dollar check had already arrived from the state and that project expenses continue to track against the budget. On the tax credit specifically, the representative said CLA has the final IRA tax credit documentation prepared and is in the midst of final audit checks, expected to take one to two weeks. The confirmed value: $2.17 million, modestly above the roughly $2 million figure the project had been tracking toward.
The deliberation: The number drew immediate clarifying questions. One member asked the presenter to repeat the figure; another said they had initially heard "2.7" and "subconsciously wanted to hear 2.7." The presenter confirmed the number a second time.
"You emphasized the 7 maybe in the statement, but you said 2.17," one member said, underscoring the correction before the group moved on.
Procedural steps and outcome: No vote was required on this item; it was an informational update. CLA will submit its final invoice to the committee once the tax credit is formally submitted to federal authorities, a step still pending as of the meeting.
Implications and what is next: The $170,000 gap between the earlier working estimate and the confirmed value modestly improves the project's net financial position. The credit submission, and CLA's related final invoice, remain outstanding items the committee will need to close out in coming meetings.
Eleven-Month Warranty Walkthrough
Background and stakes: The project is approaching the end of its one-year construction warranty period. An 11-month walkthrough, standard practice ahead of warranty expiration, was held the Tuesday before this meeting; the committee shifted its own meeting time specifically to allow this update to be fresh.
The question before the body: Members were asked to hear a report on what the walkthrough found, distinguishing items that are outright construction defects from items that are simply underperforming or not yet resolved.
Substantive content: The project representative described the walkthrough as well attended, closing out some punch-list items while opening new ones. Two categories of concern were flagged. First, non-construction performance issues, with grass establishment cited as an example of something still being monitored but not treated as a contractor defect. Second, mechanical system problems, described as more actively contested: investigation is underway involving the commissioning agent, the mechanical engineer and contractors over reports that at least one room has been running too cold and triggering alarms. Separately, three rooms on the building's northeast side were reported running hotter than other spaces, an issue a member identified as Adam had previously raised. The representative said the controls contractor and the mechanical engineering firm Salas O'Brien are working to diagnose the temperature discrepancy.
The deliberation: A member identified as Nick asked that the commissioning agent's updated report be forwarded, noting he had not received it by email. The representative agreed to send it over. No member expressed disagreement with the overall characterization of outstanding items; the discussion centered on tracking and documentation rather than dispute over responsibility at this stage.
"If you wouldn't mind just sharing that commissioning report, I don't think I saw that in my inbox," Nick said, prompting the representative's commitment to forward the document.
Procedural steps and outcome: No vote was taken. The representative said the goal is to resolve the remaining exterior items and the HVAC-related items identified in the walkthrough within the next few weeks, before the close of the one-year warranty period, so the issues can be addressed "and put a bow on it" ahead of summer.
Implications and what is next: The HVAC temperature complaints and the alarm-triggering cold-room reports remain open investigations involving multiple parties: a commissioning agent, a mechanical engineer, the controls contractor and Salas O'Brien. Whether these are deemed warranty-covered construction defects or separate performance issues will determine who bears remediation costs, and that determination is expected before the warranty period lapses.
Invoice and Payment Requisition Approval
Background and stakes: With the project moving toward closeout, several vendors and consultants continue to submit invoices for completed or ongoing work, some of it administrative backlog rather than new work.
The question before the body: Members were asked to review and vote on an invoice packet covering multiple vendors plus a construction payment requisition from the project's general contractor.
Substantive content: The representative detailed invoices from BVH, Salas O'Brien and the commissioning agent, noting the latter two still have open items tied to long-tailed measurement and verification work, meaning additional invoices are expected over the coming months. Closeout invoices from CDW were described as covering IT equipment scope "long since installed," with the invoice itself delayed in processing rather than reflecting new work; quality-assurance and quality-control checks on that scope were only recently completed, clearing the way for approval. CLA has remaining balance on its contract but will hold its final invoice until the tax credit submission is complete. Colliers submitted its monthly billing, and Gilbane, the project's general contractor, submitted payment application 27. The combined total presented for approval: $44,087.23, broken into $20,590.28 for BVH, CDW, CLA and Colliers combined, and $23,496.95 for the Gilbane payment requisition.
The deliberation: A member identified as Sharon read the formal motion language into the record once asked to do so by the chair. A brief procedural hiccup occurred when the chair appeared to click the wrong screen-sharing button before the vote, drawing a quick "Are you sure?" exchange, but the substance of the vote was not affected.
"I'd like to make a motion to approve invoice packet dated 6-29-26, including invoices from BVH, CDW, CLA, and Collier's, in the amount of $20,590.28, and a construction payment requisition 27 from Gilbane, in the amount of $23,496.95, for a total approval of $44,087.23," Sharon said.
Procedural steps and outcome: A member identified as Woody seconded the motion. The vote passed unanimously by voice vote ("aye"), with no discernible dissent or abstention recorded in the audio.
Implications and what is next: The approval authorizes payment of $44,087.23 across five vendors tied to the project's design, IT, financial-consulting and construction-management work, continuing the committee's routine closeout cadence as the project nears full financial wrap-up.
Public Comment and Remarks
Background and stakes: The agenda included a standing public comment period and a remarks item, both standard closing procedures.
The question before the body: Whether any member of the public wished to speak, and whether committee members had closing remarks.
Substantive content: The chair noted no one appeared to have joined the meeting to offer public comment. During remarks, one member wished the group a good Fourth of July holiday; no other substantive remarks were offered.
Procedural steps and outcome: A motion to adjourn was made and seconded, and the meeting adjourned on a unanimous voice vote.
Implications and what is next: No further business was scheduled or referenced for a specific future date in this meeting; the committee's next actions will likely include the forwarded commissioning report, continued HVAC troubleshooting, and eventual submission of the IRA tax credit documentation once CLA's audit concludes.
WHO WAS THERE
A committee member identified in the transcript only as Sharon, who read the invoice-approval motion. Role not specified in available sources.
A committee member identified only as Woody, who seconded the invoice-approval motion and the adjournment motion. Role not specified.
A committee member identified only as Nick, who requested the commissioning agent's report. Role not specified.
A committee member identified only as Adam, referenced by another speaker as having raised the northeast-room temperature issue; did not speak directly in the available transcript excerpt. Role not specified.
An unnamed project representative who delivered the financial, tax-credit and warranty-walkthrough updates and presented the invoice packet; no name or title for this person appears in the transcript or supplied materials.
No roster, agenda, packet or minutes were supplied for this meeting, so officer titles (Chair, Vice Chair, etc.) cannot be confirmed for any speaker.
No members of the public joined to offer comment.
ORGANIZATIONS AND DOCUMENTS REFERENCED
CLA — consultant handling the project's Inflation Reduction Act tax credit audit and documentation; confirmed the credit's final value at $2.17 million and will submit its own final invoice once the credit is formally submitted.
BVH — vendor invoiced as part of the June 29 invoice packet; role in the project not further specified in the transcript.
CDW — vendor that supplied IT equipment; its closeout invoice was delayed administratively despite the equipment having been installed previously.
Colliers — submitted monthly billing as part of the invoice packet; role in the project not further specified in the transcript.
Gilbane — the project's general contractor, which submitted payment application 27, the largest single item in the approved invoice packet.
Salas O'Brien — mechanical engineering firm involved, alongside the controls contractor, in diagnosing the reported temperature discrepancy in northeast-side rooms.
Commissioning agent (unnamed firm) — provided an updated report on warranty-period mechanical issues; the report had not yet reached at least one committee member by email as of the meeting.
Invoice packet dated 6-29-26 — the document approved by motion, totaling $44,087.23 across BVH, CDW, CLA, Colliers and Gilbane's payment requisition 27.
Eleven-month warranty walkthrough report — cited throughout the meeting as the source of the punch-list items and new mechanical and exterior issues under discussion; not entered into the record as a standalone document in this meeting.
Share this story
Know someone in Madison who follows town government? Share Townbrief Madison: they can sign up free.